U.S. IPO Recap Week of 10/16/2026
 Eric Friedman
This week's IPO recap highlights Iambic Therapeutics and City Therapeutics, which raised $350 million combined, showcasing strong market demand and execution strategies.
Coverage: Traditional U.S. operating-company IPOs of at least $100 million
1. Executive Summary
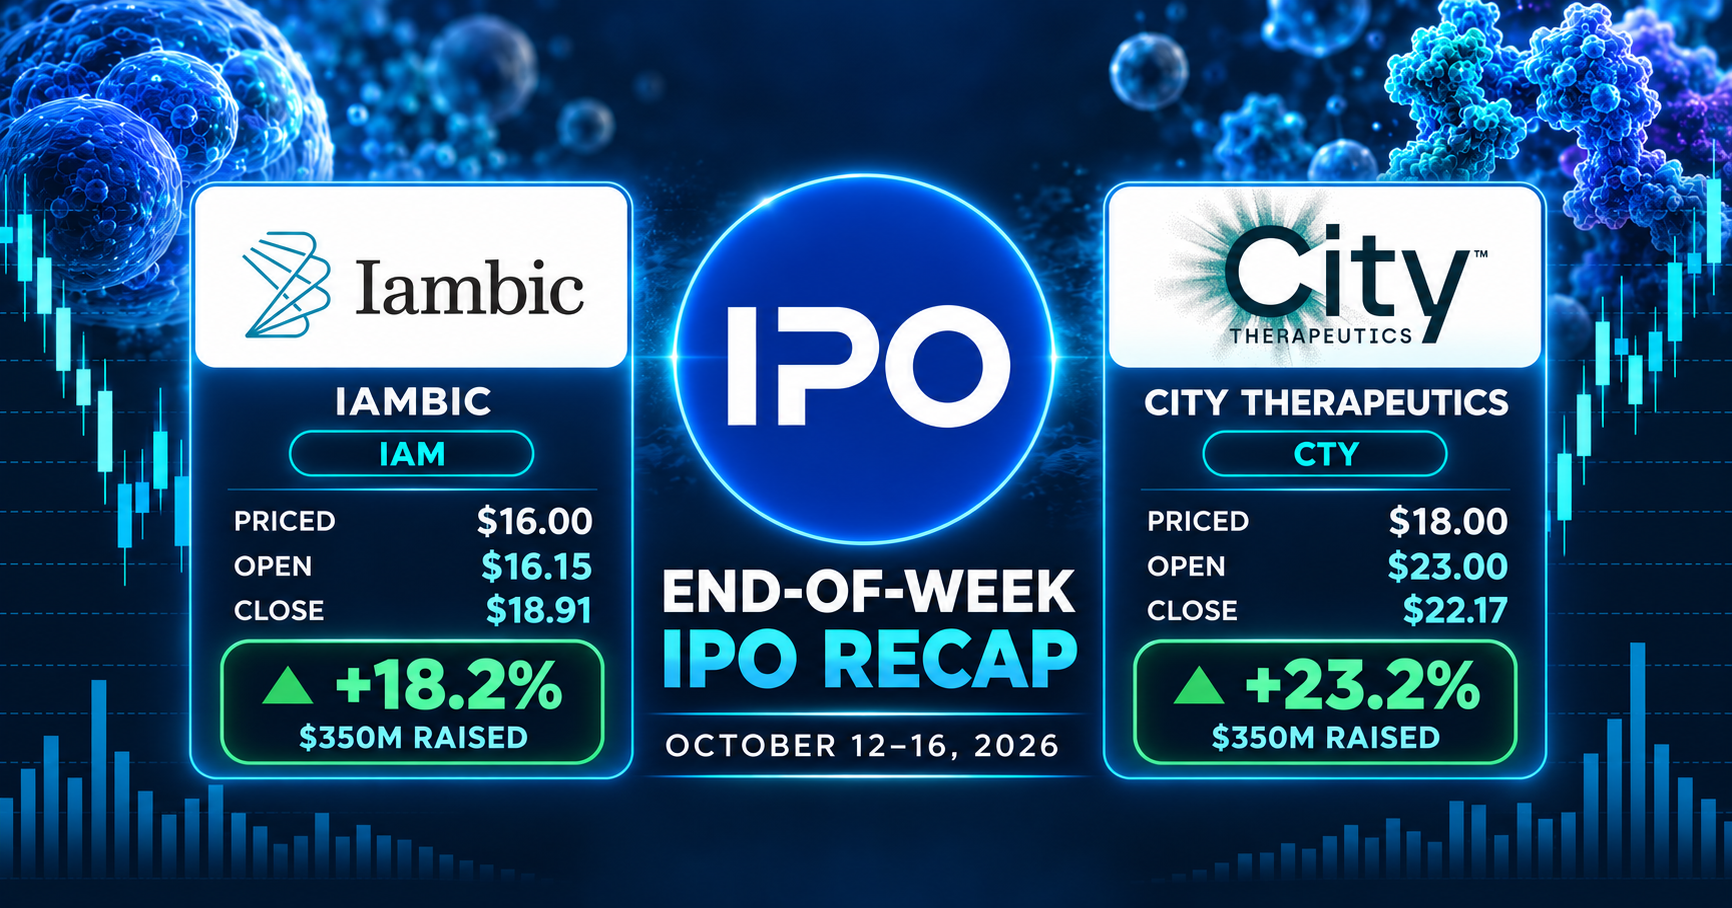
Two qualifying IPOs priced and began trading this week: Iambic Therapeutics and City Therapeutics. They raised a combined $350 million. Both priced at the midpoint of their marketed ranges, and City increased its base deal by 14.3%. The resulting tapes were substantially stronger than the prior week: Iambic closed its first day 18.2% above issue and City closed 23.2% above issue.
IPO Prophet® finished the week with a 42 WARM Heat Index. Iambic carried a 7.83 pre-offering rating and City a 7.55 rating. Both outcomes showed that modest float, specialist sponsorship and disciplined midpoint pricing can create durable first-day scarcity even in an otherwise selective market.
2. Weekly Scorecard
| Issuer | Final vs. range | Shares / offer | Open | High | Low | Close | Day-one return |
|---|---|---|---|---|---|---|---|
| Iambic Therapeutics (IAM) | $16.00 vs. $15-$17 | 9.375M / $150.0M | $16.15 | $19.70 | $16.15 | $18.91 | +18.2% |
| City Therapeutics (CTY) | $18.00 vs. $17-$19 | 11.111M / $200.0M | $23.00 | $23.88 | $20.62 | $22.17 | +23.2% |
3. Deal Analysis
Iambic Therapeutics (IAM)
Final terms and execution. Iambic sold 9.375 million primary shares at $16.00, the midpoint of its $15-$17 range, raising $150 million. The base share count was unchanged. J.P. Morgan, Jefferies, BofA Securities and Citigroup were joint bookrunners, and the shares began trading October 15 on Nasdaq.
Institutional demand and book strength. ARK Investment Management and Duquesne Family Office had indicated for up to $60 million, approximately 40% of the base deal. The midpoint pricing and intact share count showed that this anchor demand translated into a sufficiently broad institutional book without requiring a concession.
Float, scarcity and issuance-day dynamics. The 9.375 million-share float was modest, and long-duration strategic and crossover participation tightened effective supply. IAM opened at $16.15, only 0.9% above issue, then expanded to a $19.70 high and closed at $18.91. The premium developed after the open rather than being fully capitalized into the opening print.
Aftermarket performance. IAM closed its first day 18.2% above issue. On Friday it rose another 24.5% to $23.55, leaving it 47.2% above the IPO price. The second-day acceleration confirms that the original allocation did not satisfy demand and that scarcity strengthened after price discovery.
IPO Prophet® and strategy lesson. Iambic is a strong example of an opening print that understated the eventual imbalance. The useful signals were midpoint pricing, intact shares, disclosed anchor demand and persistent buying after the modest open. IPO Prophet® rated the deal 7.83, and the tape confirmed that demand quality and post-open sponsorship mattered more than the size of the initial opening premium.
City Therapeutics (CTY)
Final terms and execution. City priced 11,111,111 shares at $18.00, the midpoint of its $17-$19 range, raising $200 million. The deal was upsized 14.3% from 9.72 million shares and approximately $175 million at midpoint. Goldman Sachs, Jefferies, Stifel and Oppenheimer were joint bookrunners. The shares began trading October 16 on Nasdaq.
Institutional demand and book strength. The upsize at midpoint is the clearest book-strength signal of the week. City did not disclose a large cornerstone block comparable with Iambic, so the added 1.39 million shares indicate broader institutional demand rather than reliance on one visible anchor.
Float, scarcity and issuance-day dynamics. Despite the upsize, the 11.11 million-share base remained manageable. IPO Prophet® recorded a $23.00 opening price, 27.8% above issue. CTY reached $23.88, traded down to $20.62 and recovered to close at $22.17. The opening captured more of the imbalance than Iambic, producing a stronger initial print but more two-way trading afterward.
Aftermarket performance. CTY closed 23.2% above issue but 3.6% below its opening price and 7.2% below the intraday high. The close preserved most of the issuance premium despite the afternoon retracement, a constructive outcome for an upsized early-stage biotechnology deal.
IPO Prophet® and strategy lesson. City demonstrates that a genuine upsize can coexist with scarcity when specialist demand expands faster than supply. IPO Prophet® rated the deal 7.55. The lesson is to distinguish an upsize supported by breadth and midpoint pricing from an upsize that exhausts demand; CTY retained a substantial premium even after the larger deal cleared.
4. Underwriter and ECM Trends
Jefferies participated in both transactions, while J.P. Morgan led Iambic and Goldman Sachs led City. Both syndicates converted modest marketed floats into clean midpoint pricings, and City used demand to increase proceeds rather than push valuation to the top of the range. That execution left room for public investors and supported price discovery.
The pair raised $350 million during a risk-off session for the broader market. Healthcare specialists absorbed consecutive clinical-stage deals, indicating that biotechnology capital is available when float, sponsorship and valuation are aligned. This does not yet establish equivalent demand for large consumer, technology or sponsor-exit transactions.
5. Health of the IPO Window
The IPO window improved materially this week but remains narrow. Midpoint pricing, a successful upsize and retained first-day premiums are healthier than the low-end and flat-close result from TRex Bio one week earlier. The evidence supports an open biotechnology window; broader market health still requires successful execution from larger, later-stage operating companies outside healthcare.
6. Q4 ECM Watchlist
Each issuer below has a current public S-1 or F-1. Completed IPOs, sub-$100 million offerings, SPACs, direct listings, reverse mergers and shell-company uplistings are excluded. Postponed qualifying issuers remain listed because their registrations remain active and a Q4 re-launch is possible.
| Issuer | Verified filing status | Terms / venue | IPO Prophet® focus |
|---|---|---|---|
| Aspen Neuroscience (ASPE) | Public S-1 filed Oct. 9 | Terms pending; Nasdaq intended | Cell-therapy clinical risk, specialist demand, cash runway and float |
| Bambusa Therapeutics (BBTX) | Public S-1 filed Oct. 9 | Terms pending; Nasdaq intended | Early-stage biotech risk, institutional sponsorship and scarcity |
| Oura (OURA) | Public S-1; postponed Sept. 29 | Formerly $40-$44; 50.0M; Nasdaq | Re-launch timing, 73% secondary supply, valuation and retained demand |
| Aggreko (AGKO) | Public F-1; amended Sept. 17 | Terms pending; NYSE | Power-deman
Related Posts |