Oura (OURA) IPO: Three Numbers Investors Should Watch
 Eric Friedman
Oura has the growth, brand recognition and recurring revenue investors look for, but there are three numbers that tell us much more about this IPO than the headline numbers alone.
Oura, Inc. plans to sell 50.0 million shares at an expected price of $40.00 to $44.00 per share and list on the Nasdaq Global Select Market under the ticker OURA. At the $42.00 midpoint, the offering would raise approximately $2.10 billion and value the company at approximately $13.48 billion. Goldman Sachs, Morgan Stanley and J.P. Morgan are leading the offering.
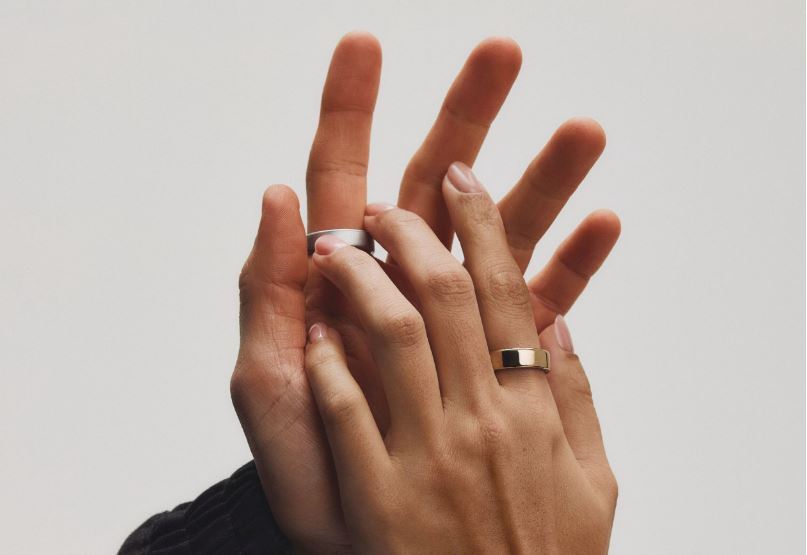
There is a lot to like about Oura. The company has built one of the most recognizable brands in wearable health technology, revenue is growing quickly, and millions of people are not only buying its rings but paying for an ongoing membership. This is exactly the kind of company that should attract attention from both institutional and retail investors.
But a popular product does not automatically make an attractive IPO. The price still matters, the structure of the offering matters, and investors need to understand what kind of business they are actually buying.
For Oura, we think there are three numbers that help tell that story: $13.48 billion, 20% and 73%.
The first number is $13.48 billion, which is Oura’s approximate market value at the $42.00 midpoint.
Oura generated $1.21 billion in revenue during the nine months ended June 30, 2026, up 74% from $697.6 million during the same period last year. On a trailing 12-month basis, the company produced approximately $1.42 billion in revenue. That means investors are being asked to value Oura at roughly 9.5 times trailing revenue at the midpoint, before accounting for additional potentially dilutive securities.
That is a serious valuation, even for a company growing this quickly.
Oura recently became profitable, generating net income of $60.8 million during the latest nine-month period compared with $1.6 million a year earlier. Its overall gross margin also improved to 55% from 51%.
Those are strong numbers, but investors are not paying $13.48 billion for the earnings Oura produces today. They are paying for what the company might become. To support this valuation, Oura will need to continue growing rapidly, maintain its position in the smart-ring market and turn its membership business into a much larger source of recurring profit.
That brings us to the second number: 20%.
Membership revenue accounted for approximately 20% of Oura’s total revenue during the nine months ended June 30. Hardware generated $974.0 million, while memberships contributed $240.5 million.
The membership business is important because it produced an 89% gross margin during the period. That is a very different business from manufacturing and selling physical rings.
Oura had 5.0 million paid members as of June 30, twice the 2.5 million it had one year earlier. Approximately 94% of ring activations have historically converted into paid memberships, and the company reported weighted-average 12-month member retention of approximately 85%.
People also appear to use the product. Members wore their rings for a median of approximately 23 hours per day and opened the Oura app an average of more than 3.5 times per day during the first three quarters of fiscal 2026.
This is probably the most important part of the Oura story. The company does not want to be viewed as another consumer-hardware manufacturer that needs to introduce a new device every few years to keep customers coming back. It wants to be viewed as a health platform with recurring, high-margin subscription revenue.
The question is whether membership revenue can become a much larger percentage of the overall business.
Right now, approximately 80% of revenue still comes from hardware. Membership growth is also tied closely to the number of rings the company sells. If ring sales slow, new memberships could slow with them.
I