U.S. IPO Recap Week of 10/23/2026
 Eric Friedman
Lycia Therapeutics had a successful IPO, raising $317.5 million amid strong demand, highlighting the selective strength in the biotechnology sector.
Coverage: Traditional U.S. operating-company IPOs of at least $100 million
1. Executive Summary
One qualifying IPO priced and began trading this week: Lycia Therapeutics. The company raised $317.5 million after increasing the base share count by 20.0% and pricing at the top of its range. LYCA opened 58.6% above issue and closed 66.7% above issue, making the week a strong biotechnology execution despite a volatile broader tape.
IPO Prophet® assigned Lycia a 7.66 pre-offering rating. The transaction paired an all-primary deal, deep specialist sponsorship and a manageable float with meaningful primary-market demand. The result confirms that scarcity can survive a material upsize when institutional demand expands faster than supply.
2. Weekly Scorecard
| Issuer | Final vs. range | Shares / offer | Open | High | Low | Close | Day-one return |
|---|---|---|---|---|---|---|---|
| Lycia Therapeutics (LYCA) | $18.00 vs. $16-$18 | 17.640M / $317.5M | $28.55 | $36.49 | $22.19 | $30.00 | +66.7% |
3. Deal Analysis
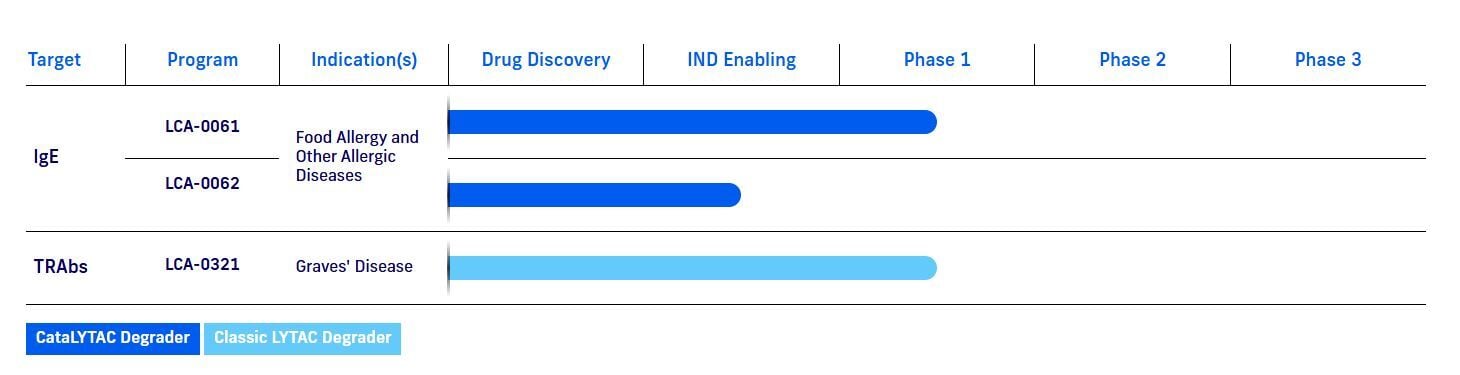
Lycia Therapeutics (LYCA)
Final terms and execution. Lycia sold 17.64 million primary shares at $18.00, the top of its $16-$18 range, raising approximately $317.5 million. The base share count increased from 14.7 million by 20.0%, adding $52.9 million of proceeds versus the original top-of-range plan. Jefferies, TD Cowen, Evercore ISI and Guggenheim Securities were joint bookrunners, with LifeSci Capital as passive bookrunner. The shares began trading October 23 on the Nasdaq Global Select Market.
Institutional demand and book strength. The simultaneous share upsize and top-of-range pricing are the strongest available book signals. The pre-IPO holder base included specialist and crossover investors such as Versant Ventures, Venrock, Redmile, RTW Investments, Janus Henderson, Blue Owl, Balyasny, Adage, HBM, OrbiMed, Eli Lilly, Franklin Templeton and Invus. The syndicate monetized demand through additional primary capital without using secondary shares.
Float, scarcity and issuance-day dynamics. The 17.64 million-share base was larger than marketed but remained modest relative to the roughly 52 million shares outstanding after the offering. Because every offered share was primary and the existing specialist holders remained invested, effective tradable supply was tighter than the headline share count suggested. LYCA opened at $28.55, 58.6% above issue, then traded between $22.19 and $36.49 before closing at $30.00. The wide range shows intense two-way price discovery around a structurally scarce float.
Aftermarket performance. LYCA closed its first session 66.7% above the $18.00 issue price and 5.1% above the opening print. The recovery from the $22.19 low and close above the open show that demand reasserted itself after early allocation turnover. With only one trading session available, durable aftermarket sponsorship still needs confirmation next week.
IPO Prophet® and strategy lesson. Lycia is a high-quality validation of the IPO Prophet® framework. The most useful pre-trade signals were the 7.66 rating, top-of-range pricing, a 20% upsize, all-primary proceeds and a specialist shareholder base. The $28.55 open already capitalized substantial FOMO, so the correct issuance-day discipline was to distinguish scarcity from price risk: the stock fell more than 22% from open to low before finishing higher. Strong deals can remain tradable, but entry price still controls risk.
4. Underwriter and ECM Trends
Jefferies, TD Cowen, Evercore ISI and Guggenheim converted a late-week launch into a top-of-range, 20%-upsized transaction. The syndicate prioritized additional primary capital rather than a higher stated price or secondary liquidity. That structure left the company better funded while preserving alignment with legacy holders.
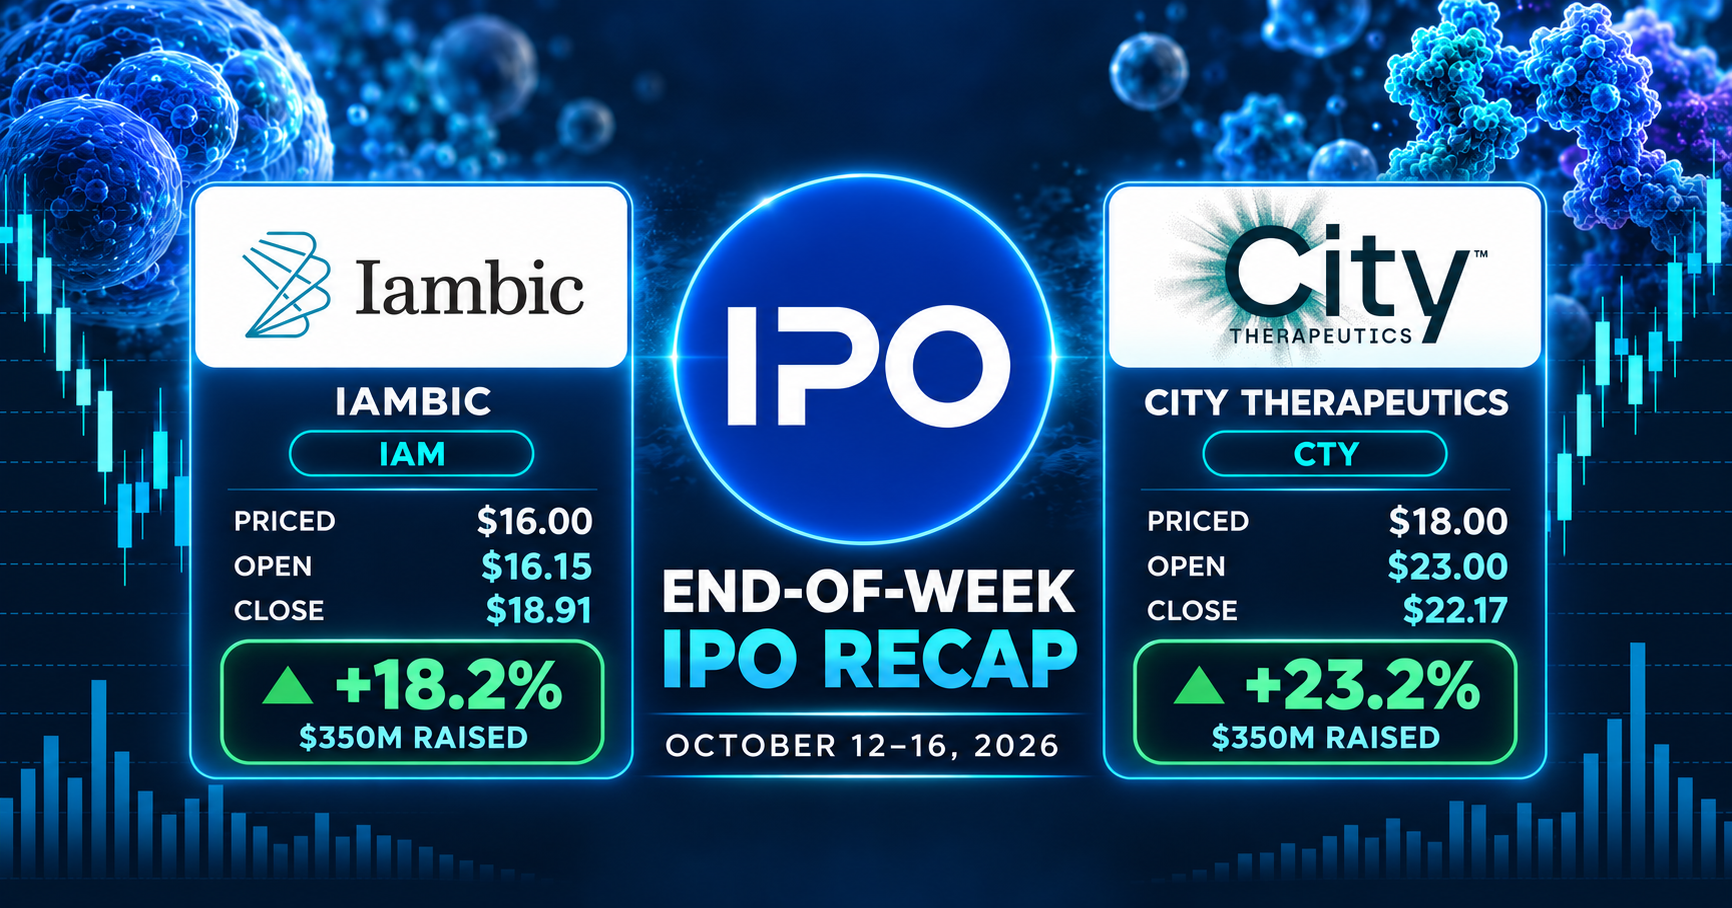
Healthcare remained the only segment demonstrating repeatable issuance strength. Lycia followed successful biotechnology offerings from Iambic and City, and its $317.5 million deal was larger than either. The market is rewarding specialist-backed clinical stories with visible scientific differentiation, but the sharp intraday reversal also shows that price discovery is becoming more volatile as opening premiums expand.
5. Health of the IPO Window
The IPO window is open for select biotechnology issuers, but it is not broadly open. Lycia delivered excellent primary execution and a large retained premium; however, the week contained only one qualifying deal and several technology and infrastructure candidates remain delayed. The strongest evidence is for targeted institutional appetite, not indiscriminate risk demand.
6. Post-Close Pipeline Development
OPay Limited (OPAY)
OPay filing announcement. OPay Limited announced after the U.S. market close that it is targeting up to $366 million in a U.S. IPO. The emerging-markets digital payments company plans to list on the NYSE under OPAY. Citigroup, Deutsche Bank, Standard Bank and CICC are among the underwriters. The announcement advances OPay from a terms-pending public filing to an active launch candidate, although the final ADS count, price range and expected trading date were not yet publicly available at publication.
IPO Prophet® read-through. OPay is the most consequential non-biotechnology pipeline development of the week. The deal will test whether institutional demand can broaden from scarce clinical-stage offerings into emerging-markets fintech. IPO Prophet® should focus on the primary-versus-secondary mix, concurrent private placement support, Nigeria concentration, regulatory exposure, currency sensitivity, float construction and whether the book can absorb up to $366 million without a valuation concession.
7. Confidential and Unfiled Pipeline
Anthropic remains a confidential SEC submission with no public S-1 on EDGAR at the close of October 23; press reports point to a possible public prospectus in late October and a mid-November offering, subject to market conditions. OpenAI also remains a confidential submission with no public S-1. Altera remains an unfiled pipeline candidate. None is represented as publicly filed.
| Issuer | Classification | Timing | Read-through |
|---|---|---|---|
| Anthropic | Confidential SEC submission; no public S-1 | Possible mid-November; unconfirmed | Major AI valuation test; monitor float, mix, price sensitivity and opening FOMO |
| OpenAI | Confidential SEC submission; no public S-1 | No confirmed 2026 launch date | Private financing may defer the IPO; monitor public filing and deal structure |
| Altera | Unfiled pipeline candidate | Potential 2026 IPO; no public terms | Large semiconductor candidate; preparation is not a public filing |
8. Q4 ECM Watchlist
Each issuer below has a current public S-1 or F-1. Completed IPOs, sub-$100 million offerings, SPACs, direct listings, reverse mergers and shell-company uplistings are excluded. Postponed qualifying issuers remain listed because their registrations remain active and a Q4 re-launch is possible.